
YOUR DMV MILITARY & VETERAN HOME GUIDE
Moving to the DMV or finally putting down roots here?
Whether your PCS orders are bring you to the Washington, DC area, you’re transitioning out of active duty, working in the federal government after military service, or simply ready for your next home, the DMV can be a lot to figure out.
DC, Maryland and Virginia offer very different housing options, commute patterns and communities and a home that looks “close” on a map may not feel close during rush hour.
I created this guide to help you get oriented, ask the right questions and start your home search with a plan.
Tammarra Peacock, REALTOR®
Licensed in DC • Maryland • Virginia
RLAH @properties
FIRST THINGS FIRST: Let’s Make Sense of the DMV
-
Your duty station, federal workplace, or other regular destination should be one of the first things we consider.
The DMV covers a lot of ground, and you don't necessarily need to live in the same city, county, or state where you work. What matters is understanding how your location affects your commute and housing options.
Start with: Where will you be working or stationed most often?
-
Twenty miles in the DMV doesn't necessarily mean a 20-minute drive.
Traffic patterns, bridges, Metro access, toll roads, installation entrances, parking, and the time you report to work can all change what a commute actually feels like.
Before we narrow your search, decide what you're realistically willing to commute on a normal workday.
DMV Tip: Check potential routes during the actual hours you'd be traveling not Sunday afternoon.
-
What you're approved to spend and what you actually want to spend every month can be two very different numbers.
Consider the complete cost of housing not just the purchase price including your mortgage payment, taxes, insurance, HOA or condo fees when applicable, utilities, commuting costs, and maintenance.
The goal isn't simply to buy the most house you're approved for. It's to find a home that fits your life.
-
You don't have to know yet.
If you're PCSing, your expected time in the area may influence the decision. If you've transitioned from military service and are now working in the federal or private sector, you may be thinking about putting down longer-term roots.
We'll look at your timeline, finances, housing needs and future plans before deciding what makes sense for you.
No pressure to buy just because you can.
Section 2: Where will you be working?
WASHINGTON, DC
Joint Base Anacostia-Bolling
Washington Navy Yard
Pentagon-area and other federal commuters
DC is also home to numerous federal agencies and defense-related workplaces, so you don't have to be active duty for this guide to apply to you.
MARYLAND
Joint Base Andrews
Prince George's County
Fort George G. Meade
Anne Arundel County
NSA Bethesda / Walter Reed area
Montgomery County
Working elsewhere in Maryland? That's okay. Your actual workplace becomes our starting point.
VIRGINIA
The Pentagon
Arlington
Joint Base Myer-Henderson Hall
Arlington
Fort Belvoir
Fairfax County
Marine Corps Base Quantico
Prince William/Stafford area
No longer active duty?
If you've transitioned into a federal, contractor, or private-sector career, we'll use your workplace and your priorities exactly the same way then explore housing options across DC, Maryland and Virginia that meet the criteria you give me.
Section 3: The DMV Commute Is Different
Around here, miles don’t tell the whole story.
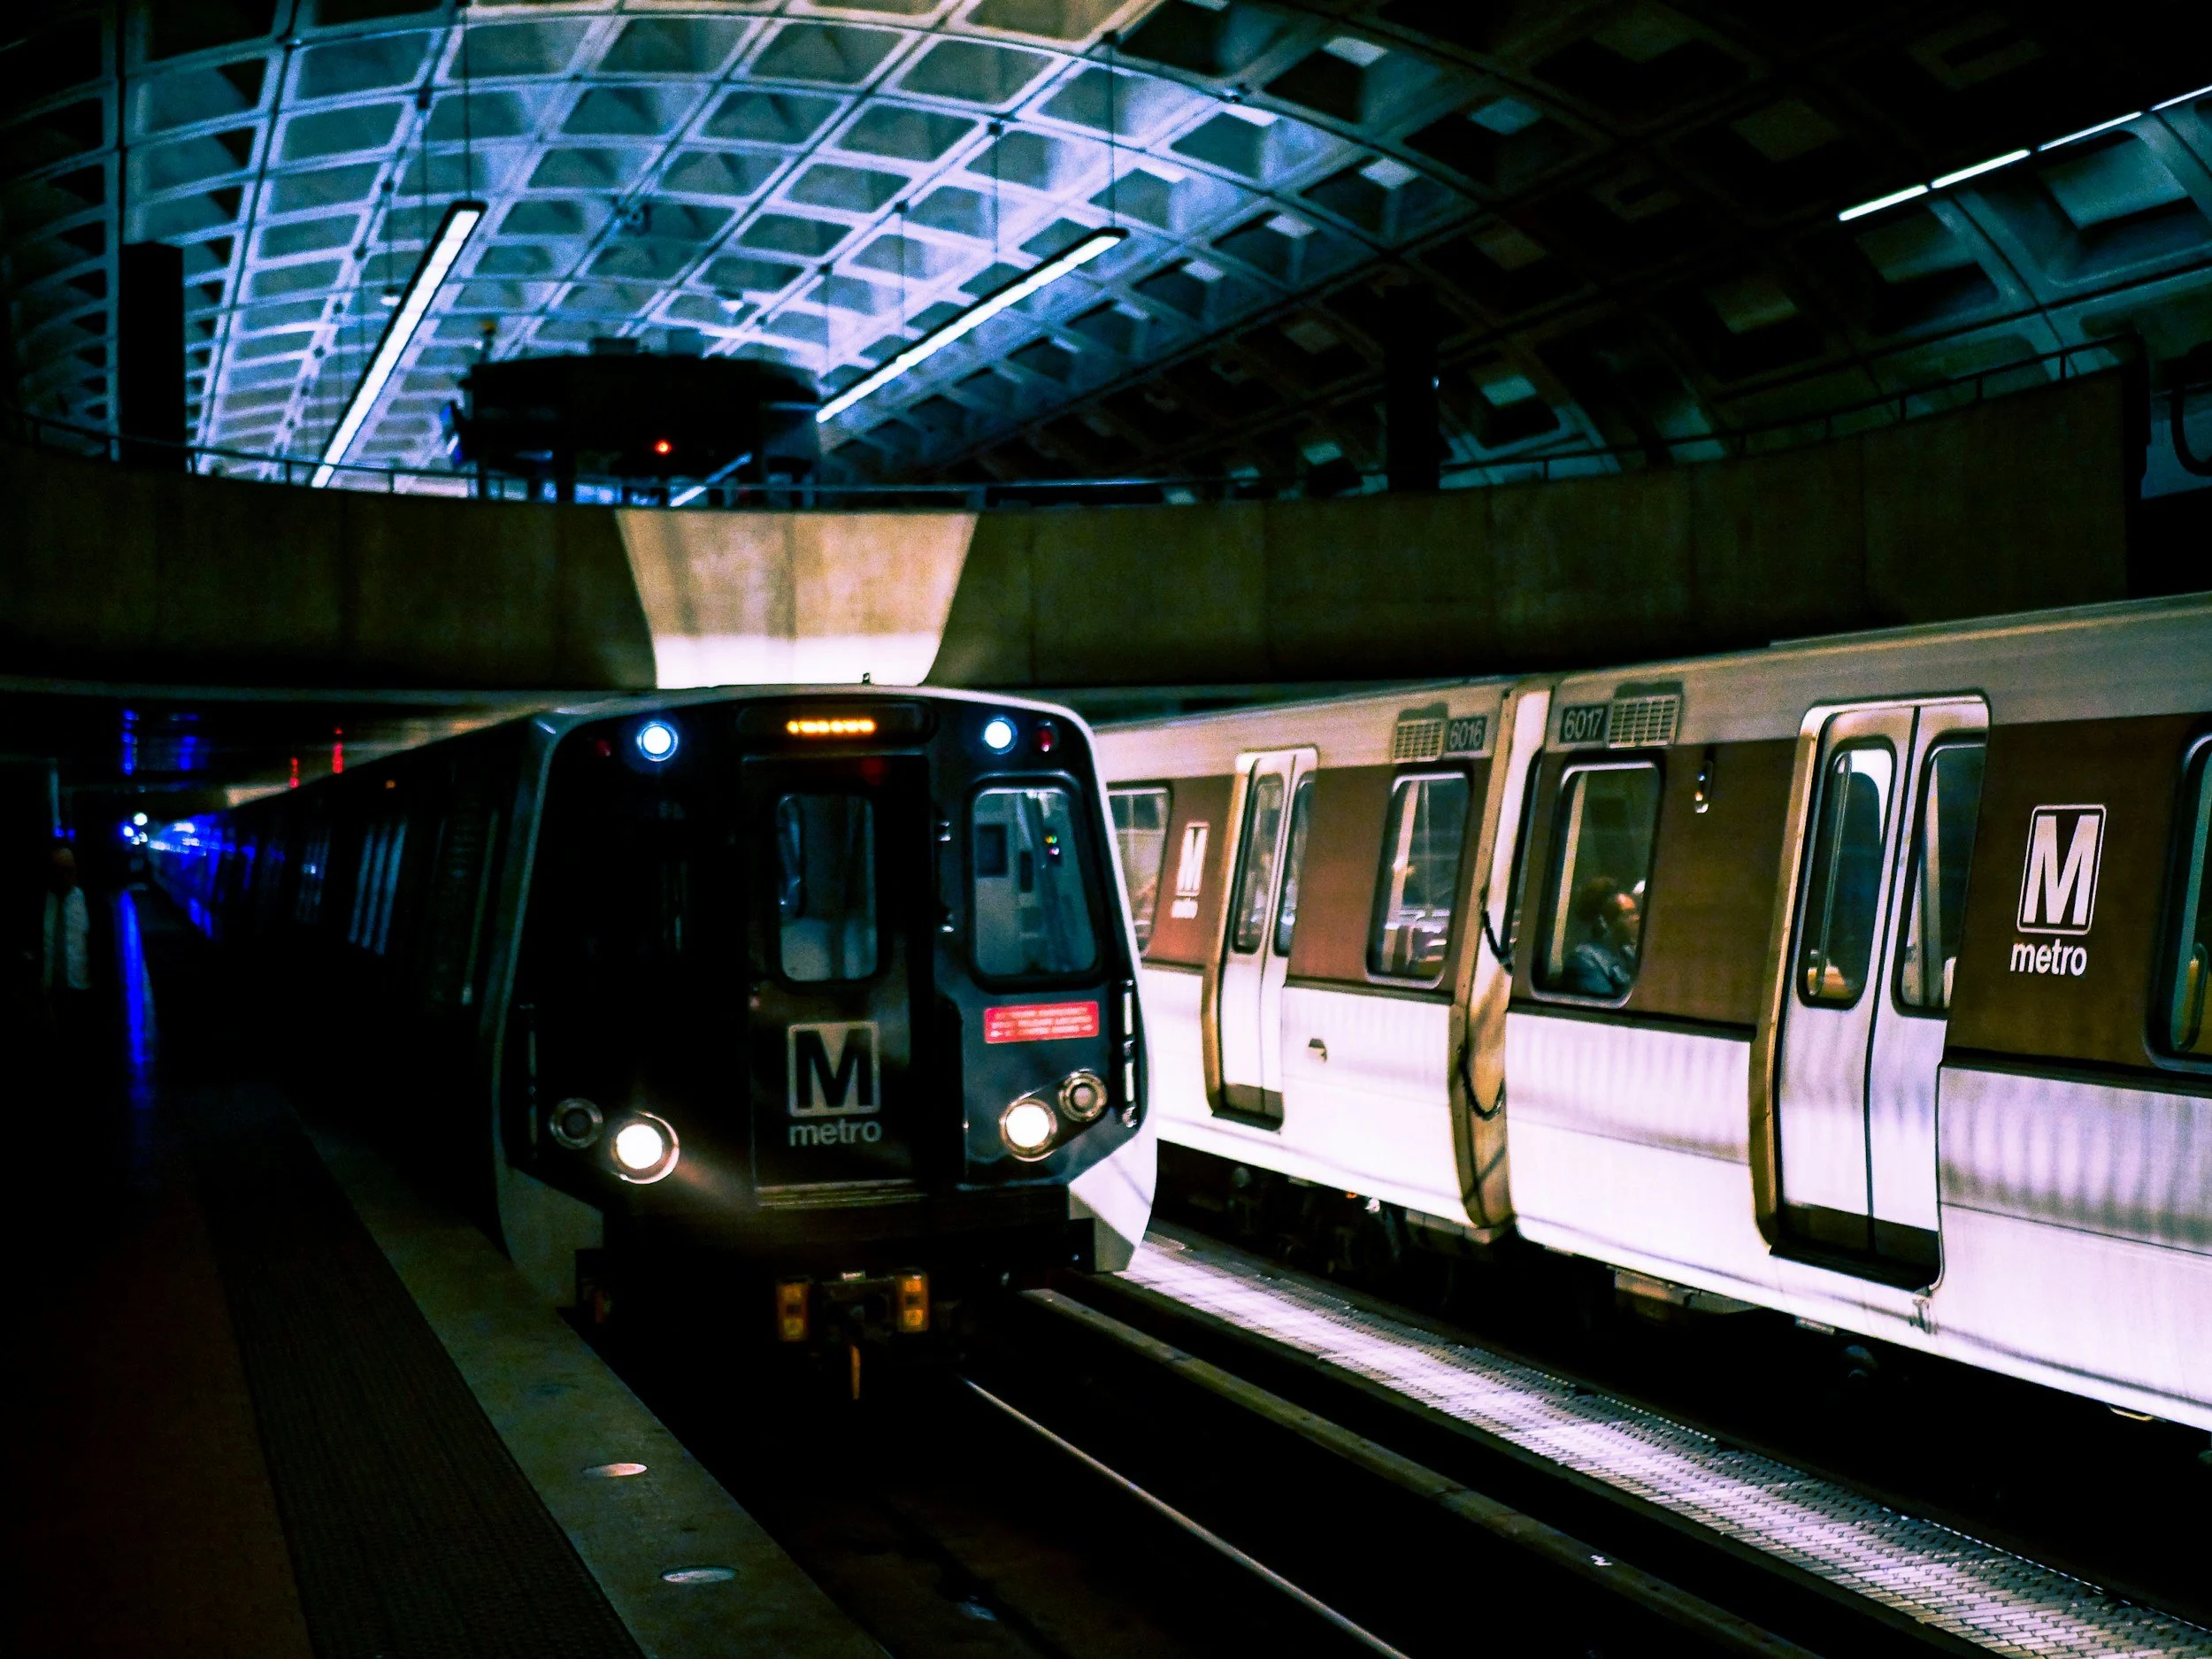
A home can look close to your duty station or workplace on a map and still create a commute you don't want to make every day.
In the DMV, your commute can be affected by:
Traffic patterns: The direction and time you travel can make a major difference.
Bridges & bottlenecks: Crossing the Potomac or relying on a heavily traveled corridor can add time.
Metro & commuter rail: Depending on your workplace and schedule, Metro, MARC or VRE may give you another option.
Tolls: Some Virginia and regional routes may involve tolls, so factor those costs into your regular commute.
Installation access: Getting to an installation isn't necessarily the same as getting through the gate and to your workplace.
TAMMARRA'S DMV TIP
Before you fall in love with an area, test the commute during the hours you'd actually travel. A 15-mile commute at 2 p.m. may look very different at 7 a.m.
We'll use your actual commute tolerance not just a radius on a map to help narrow your search.
Section 4: DC, Maryland or Virginia?
One DMV. Three different housing markets.
WASHINGTON, DC
If being closer to the city or having access to public transportation matters to you, DC may be part of your search.
Things to consider:
• Condos, rowhomes and other urban housing options
• Metro and public transportation access
• Parking
• Condo/HOA fees when applicable
• Amount of indoor/outdoor space you want
• Your commute
• DC-specific purchasing and closing considerations
Good fit when: the available housing, commute and lifestyle features match the priorities you've given me.
MARYLAND
Maryland gives you a wide range of housing environments—from areas close to DC to communities farther into Prince George's, Charles, Montgomery and Anne Arundel counties.
Things to consider:
• Commute route and travel time
• Metro or MARC access where applicable
• Property type and lot size
• Property and applicable local taxes
• HOA/community amenities
• Parking
• Proximity to the things you use regularly
Good fit when: you're looking for housing options that match your budget, space needs and commute requirements.
VIRGINIA
Northern Virginia ranges from highly urban areas close to DC to suburban and lower-density communities farther south.
Things to consider:
• Metro or VRE access where applicable
• I-95, Route 1 and other commuting corridors
• Tolls along routes you may regularly use
• Condo/HOA fees where applicable
• Property type and available space
• Parking
• Commute time
Good fit when: the available housing and transportation options align with your priorities.
Here's where having one REALTOR® licensed in DC, Maryland AND Virginia helps.
Your search doesn't have to stop at a state line. We can compare options across the DMV based on the things you've told me matter to you—budget, commute, property type, transportation, space and other requested features.
Section 5: Buy or Rent?
The right answer depends on more than your orders.
If you're moving to the DMV, you may hear plenty of opinions about whether you “should” buy.
I prefer to start with questions.
How long do you reasonably expect to be here?
What would a comparable rental cost?
What monthly housing payment are you comfortable carrying?
How much cash do you want to keep available after your move?
If your plans change, would you be comfortable owning the property?
If you're no longer active duty, are you planning to make the DMV home for the foreseeable future?
Buying isn't automatically the goal. Making an informed housing decision is.
Whether buying or renting makes sense depends on your individual circumstances. I'll help you understand the real-estate side, while your lender can help you evaluate your financing options.
Section 6: VA Home Loan Basics
You've earned the benefit. Let's make sure you understand the basics.
A VA-backed home loan can be a valuable option for eligible service members, Veterans and certain surviving spouses. Your individual eligibility, financing and loan terms should always be confirmed with the VA and a qualified VA lender.
-
Eligibility for a VA-backed home loan is based on factors including your service history and duty status.
A Certificate of Eligibility (COE) shows your lender that you meet the VA's service-related eligibility requirements. You can request a COE directly through VA, and a lender may also be able to request it for you.
Your COE is only one part of the process. You'll still need to meet VA and lender requirements for your credit, income and other financial factors.
Not sure whether you're eligible? Start with the VA rather than assuming you do—or don't—qualify.
-
A VA-backed purchase loan is made by a private lender, while the VA guarantees a portion of the loan.
For eligible borrowers, potential benefits can include:
• No down payment in qualifying circumstances
• No monthly private mortgage insurance (PMI)
• Competitive loan terms
• Limits on certain closing costsA VA funding fee may apply, although some borrowers are exempt. Your lender can explain how the fee and other costs apply to your particular loan.
Important: “No down payment” doesn't mean “no money needed.” Buyers may still have closing costs and other expenses associated with purchasing a home.
That last sentence is important because you don't want your guide promising people they can buy with $0 out of pocket.
-
Possibly, yes.
Using your VA home-loan benefit once doesn't automatically mean you're finished with it. VA says the benefit can be used again in qualifying circumstances, and entitlement can affect what options are available.
If you currently own or previously owned a home purchased with a VA-backed loan, talk with your lender and check your COE to understand your remaining or restored entitlement before assuming you can't use the benefit again.
-
This one is very important, and it's where you get to sound like the protective Realtor you are.
They're not the same thing.
A VA-approved appraiser provides an opinion of the property's value and checks that the home meets VA minimum property requirements.
A home inspection is a separate evaluation of the home's condition. The VA itself strongly recommends that buyers have a home inspected, and specifically notes that a VA appraisal is not a home inspection.
My advice to my clients: Don't mistake an appraisal for your opportunity to learn more about the condition of the home you're purchasing.
-
Some borrowers using a VA-backed loan pay a one-time VA funding fee.
Whether you pay it—and the amount—depends on factors such as the type of loan, down payment and whether you've used the VA home-loan benefit before. Certain eligible borrowers are exempt from the funding fee.
The funding fee can generally be paid at closing or financed into the loan. Your lender should explain your individual costs before you make financing decisions.
Ask your lender: “Am I exempt from the VA funding fee, and if not, what would my fee be?”
-
Before you start shopping for homes, consider asking:
Do I have full or remaining VA entitlement?
Can you obtain my Certificate of Eligibility?
What monthly payment fits the budget I gave you?
What interest rate and lender fees are you offering?
Will I owe a VA funding fee?
What cash should I realistically expect to need at closing?
How will property taxes and insurance affect my payment?
What happens if the home doesn't appraise at the contract price?
And don't be afraid to compare lenders. The VA itself advises borrowers to shop around because private lenders can offer different rates and fees.
A quick note: I'm your real-estate resource NOT your lender. VA eligibility, entitlement and financing depend on your individual circumstances. I'll help you navigate the real-estate side of your purchase and work alongside your lender throughout the transaction.
SECTION 7: LIFE AFTER ACTIVE DUTY
Your military move may be over. Your next chapter is just getting started.
For many Veterans, the DMV becomes more than a duty station.
You may have transitioned into a federal career, started working for a government contractor or private employer, built a community here or simply decided you're ready to put down roots.
That changes the home-search conversation.
Instead of planning around your next set of orders, we can start thinking about what you want your life here to look like.
WHERE ARE YOU WORKING NOW?
Your new workplace may completely change the areas that make sense to explore.
WHAT DOES “HOME” LOOK LIKE NOW?
More space? A yard? Condo living? Walkability? Less maintenance? Your priorities may be different than they were during active duty.
WHAT COMMUTE FITS YOUR LIFE?
We'll still consider the DMV commute—but now we can balance it against the lifestyle and housing features that matter to you.
ARE YOU PUTTING DOWN ROOTS?
If you're planning to stay in the region longer term, we can approach your search with those future plans in mind.
ALREADY OWN A HOME FROM YOUR TIME IN SERVICE?
Don't assume that using a VA-backed loan in the past automatically means you can't use your benefit again. Your current eligibility and entitlement depend on your individual circumstances, so check your COE and talk with a qualified VA lender about the options available to you.
You don't have to have PCS orders for me to help you.
Whether you're transitioning out of active duty, starting a federal or civilian career, moving within the DMV, buying your first home after service, or simply ready for something different, we'll start with where you are now and where you want to go next.